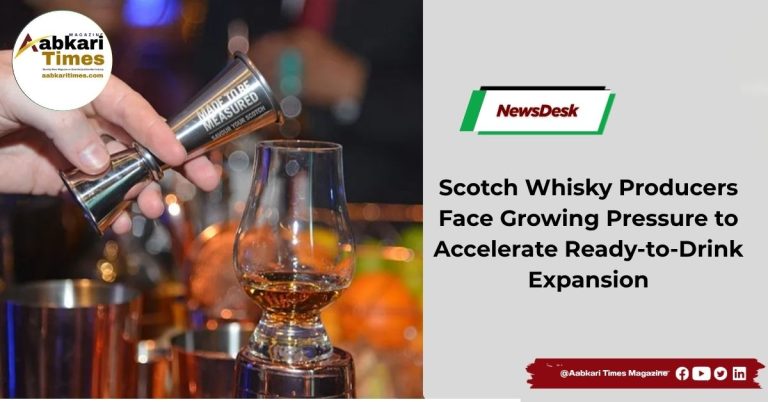
London: Scotch whisky producers are facing increasing pressure to expand into ready-to-drink (RTD) beverages and canned cocktails as the category continues to grow globally, even as broader alcohol consumption remains under pressure. Major drinks companies are increasing investment in spirit-based RTDs, driven by consumer demand for convenience, portability, smaller serving sizes and greater variety.
Diageo has highlighted RTDs as a major strategic priority, with the company reporting sales of more than 400,000 RTD products at 27 major UK festivals so far this year. The company has pointed to the growing popularity of canned cocktails at festivals, where consumers are looking for convenient formats without moving away from branded and premium drinks.
Other global spirits companies are also reporting strong momentum in the RTD segment. Pernod Ricard reported a 17% increase in RTD sales in fiscal 2026, while company executives have described the category as one of the strongest growth areas in the US market. The company sees RTDs as both a convenience-led format and an opportunity to introduce consumers to its broader spirits portfolio.
→ Aspri Spirits acquisition powers new travel retail chapter for U’Luvka vodka→ Jaisalmer Indian Craft Gin Bringing Rajasthan’s Spirit to the Global Gin Stage
Suntory Global Spirits has similarly expanded its RTD operations, particularly in Asia, using brands including Jim Beam and Japanese whisky labels. Company executives have said changing consumer occasions are influencing product development, with RTDs increasingly positioned for everyday consumption while premium spirits remain focused on more considered occasions.
Industry data also highlights the expansion of canned cocktails. Figures from IWSR cited by industry executives indicate that canned cocktails recorded compound annual growth of around 8% between 2019 and 2025. Although growth is expected to moderate to approximately 2%-3% annually over the next four years, the category continues to expand while beer, wine and traditional spirits face pressure from changing drinking habits, health considerations and household spending constraints.
Premium RTDs are also gaining traction. IWSR data indicates that premium-and-above RTDs grew 15% by volume in 2025, with products containing around 7%-10% alcohol benefiting from consumer demand. The trend represents a shift from the earlier hard-seltzer-led phase of the RTD market towards spirit-based cocktails, established brands and familiar serves packaged for convenience.
For Scotch whisky producers, however, entering the RTD segment presents several challenges. Scotch whisky must legally mature for a minimum of three years before it can be sold as Scotch whisky. This creates higher working-capital requirements compared with spirits such as vodka, gin and tequila, which can generally be used in RTD products without the same mandatory maturation period.
Brand positioning is another consideration. Scotch has traditionally been associated with ageing, craftsmanship, provenance and premium quality. Producers therefore need to balance the convenience and accessibility of canned cocktails with the established positioning of their whisky brands. The choice of whisky, flavour profile and cocktail serve can become particularly important when a premium Scotch label is extended into an RTD format.
Despite these challenges, the commercial opportunity is attracting greater attention. Whisky is already widely consumed in mixed drinks, giving producers an opportunity to capture part of that consumption through packaged cocktails. Diageo has acknowledged the need to strengthen its position in whisky-based RTDs after losing share in the broader category. The company has said its RTD market share has fallen from nearly a quarter previously to around 10%, although it remains one of the world’s largest RTD players.
The growth of whisky-based RTDs is also evident outside Scotland. Jameson has expanded its presence in the US RTD market, while Brown-Forman has reported significant global sales for Jack & Coke, its collaboration with Coca-Cola. The product has reportedly reached around 1.8 million cases globally, demonstrating the scale that established whisky brands can achieve through ready-to-drink formats.
Scotch producers have also begun testing the category. Chivas Brothers has introduced a Ballantine’s and cola RTD, while Cutty Sark has developed a Scotch and ginger ale offering. Other brands, including Bruichladdich and Wee Smoky, have experimented with premium pre-mixed serves. Diageo has also expanded its whisky-based RTD offerings, including Johnnie Walker Blonde with lemonade and Johnnie Walker Black Ruby Blackberry and Cola in Australia.
Australia, one of the world’s most developed RTD markets, has become an important testing ground for whisky-based canned drinks. The market is providing global spirits companies with insights into consumer acceptance, pricing, flavour preferences and occasions for packaged cocktails.
The growing RTD market is therefore creating a strategic challenge for Scotch whisky producers. While the category offers an opportunity to reach consumers seeking convenient and accessible drinks, producers must simultaneously manage Scotch’s maturation requirements, higher liquid costs and premium brand positioning. As canned cocktails continue to expand, the ability to combine whisky heritage with modern formats could become an increasingly important part of the global spirits industry’s product strategy
About the Author